Changed your mind after receiving a loan? Singapore’s new cooling-off rules give eligible borrowers time to reconsider. But “no interest” does not necessarily mean cancellation is free, and the fee a lender keeps is different from the total cash you must return.
Here is how to separate those amounts, with five illustrative examples.
Which loans qualify, and when does counting start?
The three-business-day cooling-off period applies to unsecured loans, other than business loans, disbursed by licensed moneylenders on or after 15 September 2026. The disbursement day, Saturdays, Sundays and Singapore public holidays are excluded from the count. Loans disbursed before that date are excluded. These details appear in licence condition 23 and its footnotes.
Contact your lender promptly to confirm your cancellation deadline and arrangements. Do not assume three business days means exactly 72 hours, or that sending a message alone completes cancellation.
What can the lender retain?
For an eligible cancellation within the cooling-off period:
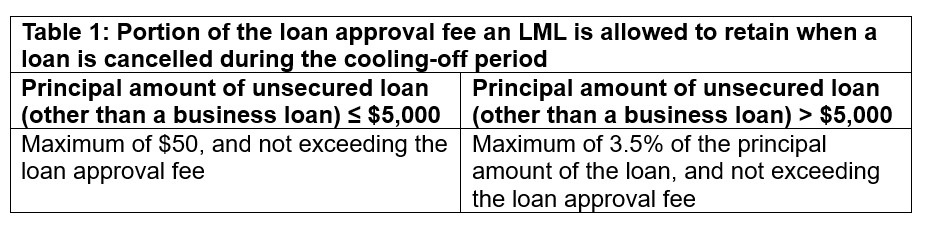
- Principal up to and including S$5,000: the maximum retained approval fee is the lower of S$50 or the approval fee actually charged.
- Principal above S$5,000: the maximum is the lower of 3.5% of the full principal or the approval fee actually charged.
These are ceilings, not automatic charges. The official fee table sets out both limits. MinLaw also confirms that no interest is charged and total repayment cannot exceed the original principal in an eligible cooling-off cancellation. See the MinLaw announcement.
Five examples: fee retained versus money returned
Every example below assumes an eligible unsecured, non-business loan, an approval fee deducted upfront, no previous repayments, valid cancellation within the cooling-off period and maximum permitted fee retention. The percentages are hypothetical, not HHL’s advertised rates. All figures are Singapore dollars.
| Principal | Upfront approval fee | Cash received | Maximum fee retained | Maximum total returned |
|---|---|---|---|---|
| S$1,000 | 3% = S$30 | S$970 | S$30 | S$1,000 |
| S$1,000 | 6% = S$60 | S$940 | S$50 | S$990 |
| S$6,000 | 6% = S$360 | S$5,640 | S$210 | S$5,850 |
| S$6,000 | 3% = S$180 | S$5,820 | S$180 | S$6,000 |
| S$6,000 | 10% = S$600 | S$5,400 | S$210 | S$5,610 |
John’s S$1,000 loan with a 3% fee
John receives S$970 after the S$30 deduction. Because the actual fee is below S$50, the lender can retain at most S$30. John returns S$970 + S$30 = S$1,000, not S$1,030. Adding S$30 to the original principal would count the fee twice.
A S$1,000 loan with a 6% fee
The borrower receives S$940. The lender may retain S$50 of the S$60 fee, so the maximum return is S$990. The other S$10 is already reflected in that reduced repayment.
Three S$6,000 comparisons
Here, 3.5% of the entire S$6,000 principal is S$210. It is not calculated only on the amount above S$5,000.
With a 6% upfront fee, S$5,640 received plus S$210 retained gives S$5,850 returned; S$150 of the fee is not retained.
With a 3% fee, the actual S$180 fee is below the ceiling. S$5,820 received plus S$180 gives S$6,000 returned.
With a 10% fee, S$5,400 received plus S$210 gives S$5,610 returned. The remaining S$390 is not retained; it is already accounted for in the lower repayment.
This approach follows the distinction between disbursed cash and retained fees in MinLaw’s worked illustrations.
What should you check before returning money?
Ask for an itemised cancellation calculation showing your principal, upfront deduction, cash received, retained fee and final amount due. Confirm the repayment arrangements and keep the receipt and cancellation confirmation. If terminology is unfamiliar, our Singapore loan glossary explains common terms.
Frequently asked questions
Is cancellation always free?
No. Interest is not charged for eligible cooling-off cancellation, but a permitted approval fee may remain.
What happens at exactly S$5,000?
The S$50 ceiling applies, limited further by the actual approval fee charged.
What if the cooling-off period has passed?
Do not assume these cancellation figures apply. Request an early-settlement breakdown under your contract; ordinary early repayment is a different situation.
Questions about an HHL loan?
Contact HHL Credit Pte. Ltd. through the official website for clarification of your loan documents. Any new loan remains subject to assessment and required in-person verification.

 Whatsapp
 Email